

A Micron Bet With Two Ways To Win
Micron was Portfolio Armor’s #1 name as of Friday’s close. AI’s appetite for memory keeps growing, Micron’s latest results support the business case, and its stock now passes our technical entry screens. We’re adding a bullish trade with an unusual attraction: it can earn a modest profit even if the shares fall 20% over the next six months.
The larger prize is a possible 200+% profit on the amount at risk—leaving us with more than three times that capital—if Micron comes within the ballpark of our system’s potential return estimate for it over the next several months.
The System Behind Friday’s #1 Name
We’ve published Portfolio Armor’s Top Ten Names weekly since launching this Substack at the end of December 2022. The system ranks stocks by their estimated returns over the next six months, net of hedging costs. Through our latest performance update, 171 completed weekly Top Ten cohorts averaged 17.98% over the next six months, versus 9.89% for SPY over the same periods. The chart below compares that broader stock-selection record.
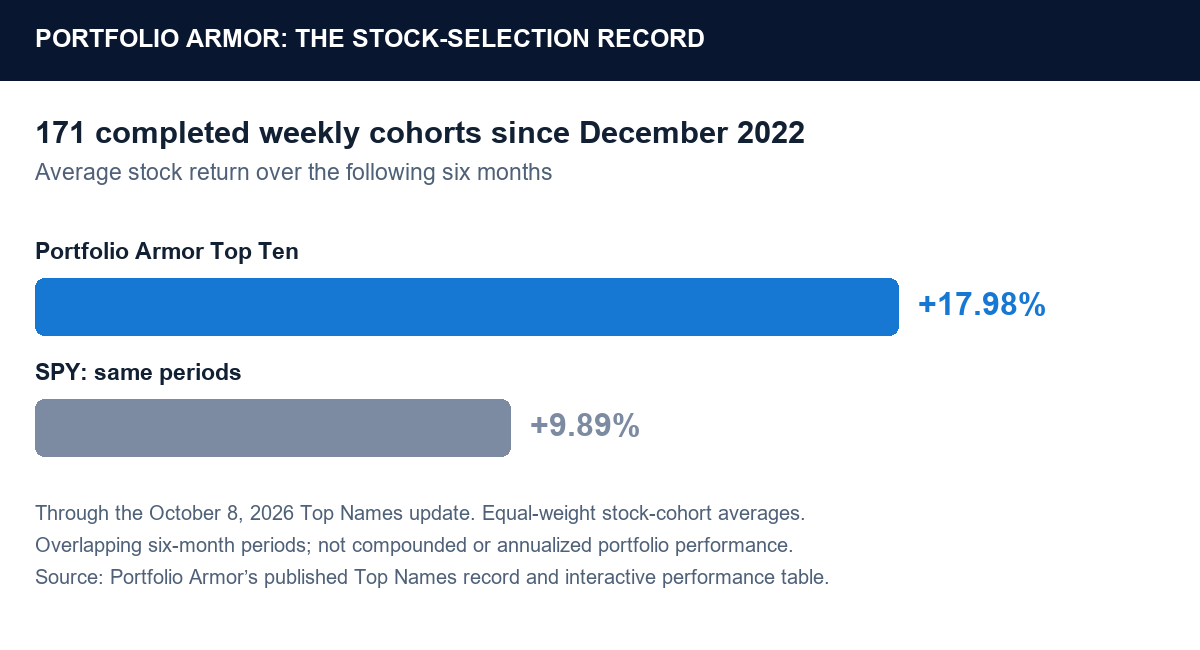
You can inspect every completed cohort in our interactive performance table.
AI Needs More Memory
We returned to Micron in July as the memory stocks were correcting. Our July 2nd alert drew on the bullish thesis from our Market Watchers list: AI systems need more memory, and suppliers can benefit when demand grows faster than capacity. That entry was early—the correction continued—but our July position remains open and is in the black now. Here’s the original alert:

Later that month, we revisited the cycle in this memory-stock discussion. The question was whether the selloff anticipated an imminent earnings peak, while demand and supply commitments suggested the upcycle had further to run:

Our view is that the earnings peak is still ahead. Micron’s September 30th results show the business accelerating: fiscal fourth-quarter revenue reached $54.23 billion, up from $41.46 billion in the previous quarter, with adjusted earnings of $33.42 per share. For the current quarter, management guided to $61.5 billion in revenue, plus or minus $1.5 billion, and adjusted earnings of $38.15 per share, plus or minus $1.
Commitments Support The Next Six Months
In its earnings-call remarks, Micron said it expects supply and demand to be tighter in calendar 2027 and 2028 than in 2026. Larger AI models, longer context windows and more simultaneous users all increase the memory required. The company said agreements cover the vast majority of its 2027 high-bandwidth memory supply, at significantly higher prices than this year.
Micron also reported 26 multi-year, take-or-pay customer agreements and $32 billion in customer commitments, mostly deposits. These commitments support our thesis that the demand has substance. Meanwhile, initial output from its first Idaho fab is expected in mid-2027, with the second following in late 2028. That timetable gives us a reason to favor a six-month trade.
At Friday’s $1,029 close, Micron traded at 13.6 times the $75.52 in adjusted earnings it just reported for fiscal 2026. In July, we argued that the timing of the earnings peak mattered more than a low multiple alone. Rising quarterly profits, higher contracted memory prices and customers committing cash for future supply give us a reason to expect more earnings growth from here.
Micron’s board also authorized up to $35.16 billion in total share repurchases, with purchases permitted from December 9th. That gives Micron a way to support its shares and increase earnings per share as profits grow.
Our Earlier Micron Trades
On December 16th, 2025, we entered a Micron combo at a $1.70 net debit. Here’s the original entry card:

We finished exiting it on December 19th for a 91% return on its original maximum risk:

On March 3rd, 2026, we entered another Micron combo at a $2.62 net debit:

We finished exiting it on May 5th for a 173% return on its original maximum risk:

The March winner is one of 261 trades we’ve fully exited this year through October 9th. Their average return on original maximum risk was 25%. You can click on the card below to see our complete trade exits record:

Why We’re Adding Now
Micron’s business is accelerating while customers lock in future supply. Its stock has returned to our #1 spot and now meets our technical entry criteria. That alignment of earnings growth, valuation and entry timing makes this a good point to add a new trade.
New to our alerts? Start here for an overview of our approach:

Today’s Top Names Trade
Theme: AI demand and committed customers extend Micron’s earnings growth.
RSI: 50; Chartmill Technical Rating: 10; Setup Rating: 7; Fundamental Rating: 8.
