

Two Prices Went Up
The Federal Reserve raised its target range by a quarter point on Wednesday, to 3.75%–4%. On the same day, customers circulated a notice from Nebius Group (NBIS 0.00%↑ ) saying its on-demand prices for NVIDIA (NVDA 0.00%↑) GPUs would rise on October 1st.
The reported increases cover both older and newer chips. The hourly price of an H100 would rise from $3.85 to $4.50, while an H200 would go from $4.50 to $5.40. B200 and B300 prices would rise to $8.50 and $9.50, respectively. Those increases range from about 17% to 21%.


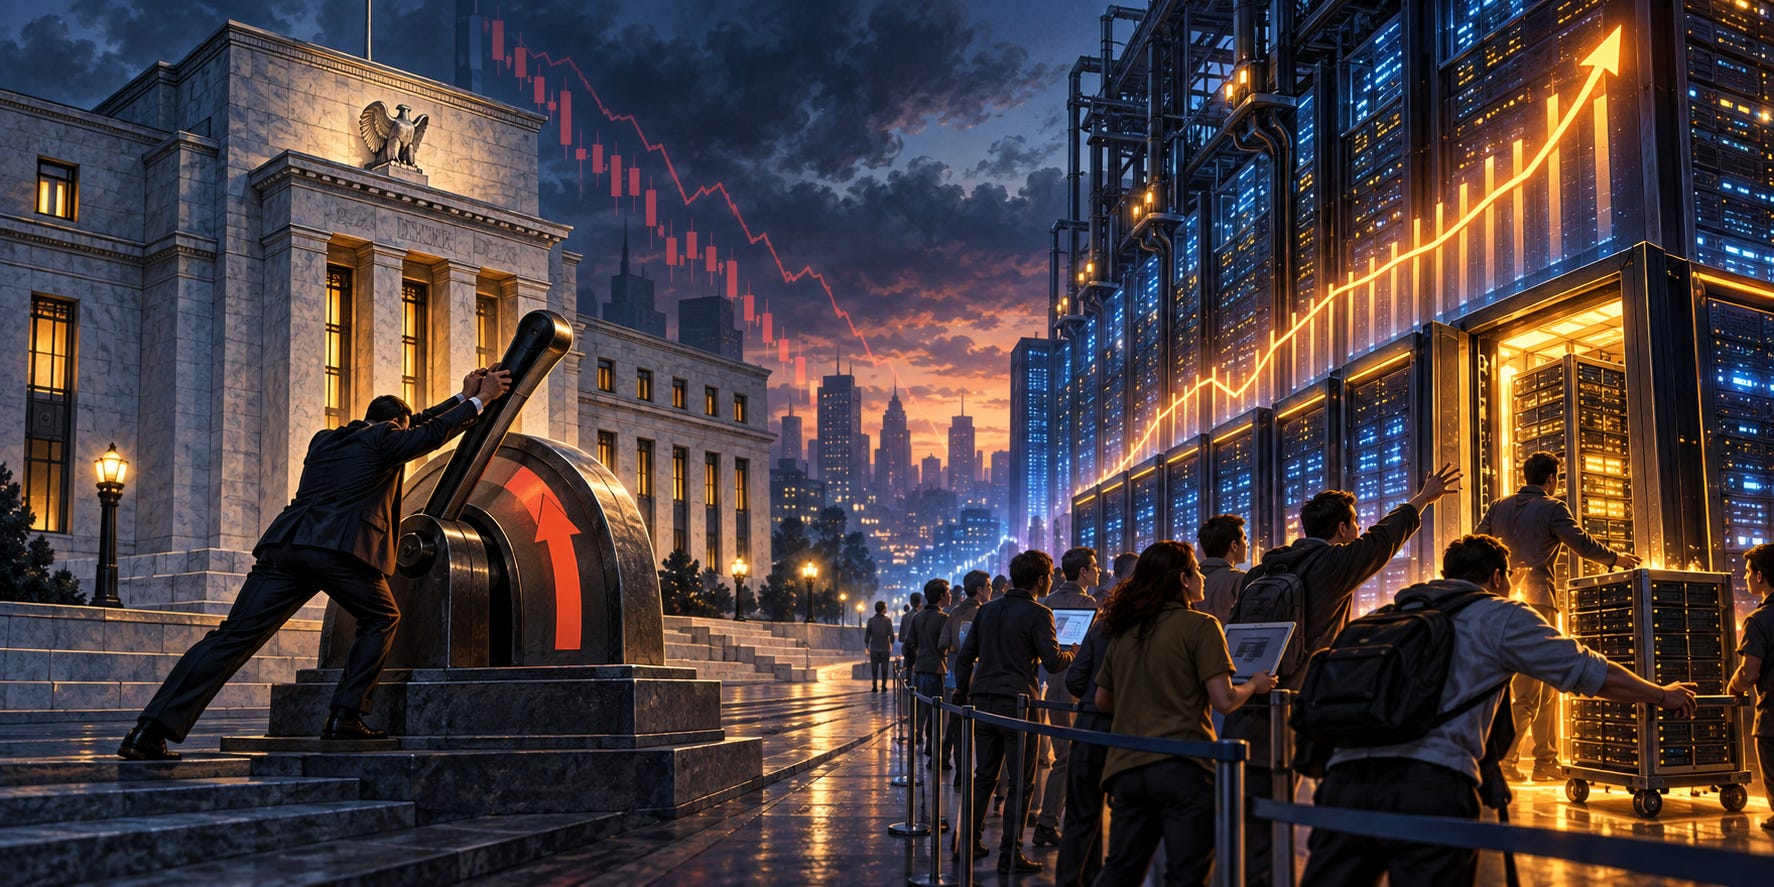
That juxtaposition captures the tension in the AI trade. The price of money is rising, which increases financing costs and reduces the present value of distant profits. The price of compute is rising too, which points to scarcity and pricing power in the infrastructure being built now.
Scarcity Is Showing Up In Orders
The same demand pressure appears elsewhere in the stack. Arm Holdings (ARM 0.00%↑) said demand for its new AGI CPU exceeds $2 billion across its 2027 and 2028 fiscal years, more than twice the amount it had disclosed earlier. Arm also said it had secured the manufacturing capacity needed to support its initial $1 billion opportunity.
Memory remains constrained as well. SK Hynix (SKHY 0.00%↑) said in its latest quarterly results that customer demand exceeded available supply. The company began shipping HBM4 during the second quarter and plans to increase production during the second half of the year.
These signals come from three different layers of the stack: GPU rentals, data-center CPUs and high-bandwidth memory. Together, they describe a market in which customers are still competing for scarce compute.
The Financing Risk Is Real
The Fed’s hike puts particular pressure on capital-intensive companies that need to finance new data centers before those facilities generate revenue. A higher cost of capital can reduce equity values even when customer demand remains strong.
Nebius has tried to match its financing to contracted demand. In July, the company raised $775 million in secured debt backed by deployed GPU infrastructure and contracted cash flows. At the time, Nebius said it had more than $40 billion of additional contracted revenue from investment-grade customers, including Microsoft and Meta.
The investment question is whether operating pricing power can outrun the higher cost of capital. Wednesday’s evidence moved both sides of that equation upward.
We’ve Traded Nebius Before
We’ve traded this theme in Nebius before. A four-leg options combo we entered on November 4th returned 211% on maximum risk when we exited it on May 13th.

We currently have another NBIS trade we entered in the alert below that’s on track for a gain as well, albeit a more modest one.

What We’ll Watch Next
On-demand GPU prices provide a useful real-time test of the AI buildout. Prices that remain firm while providers add capacity would confirm that new supply is being absorbed. Falling prices and weakening contract demand would signal that capacity is catching up.
We’ll continue looking for companies with pricing power or indispensable positions in the AI stack, and we’ll structure trades when their setups and options markets offer compelling asymmetry.
Use the button above if you’d like a heads-up when we place our next AI stack trade; click below if you’d like to learn more about the process behind our trades.
